Time Series Foundation Models in Financial Markets
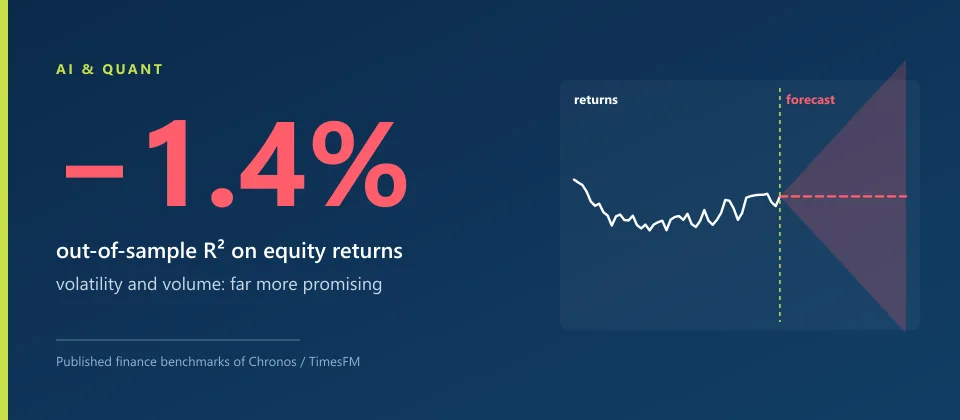
Pre-trained forecasting models top general benchmarks, but financial returns are a different beast. What Chronos-2, TimesFM and their peers can and cannot do for trading desks in 2026.
Time series foundation models, deep learning on order books, reinforcement learning for market making, ML in HFT and LLM trading agents.
Machine learning is now part of most quantitative trading stacks, but microstructure data is noisy, non-stationary and latency constrained.
We separate what works in production from what works only in papers, from foundation models and DeepLOB to reinforcement learning and LLM research agents.
Pre-trained forecasting models top general benchmarks, but financial returns are a different beast. What Chronos-2, TimesFM and their peers can and cannot do for trading desks in 2026.
Research roadmap
Our editorial plan for this section. Published guides are linked; the rest are in research.